back to insights & opinions
Recently, I caught up with a friend who lives in Dubai but is originally from London and left the UK following a significant liquidity event two years ago. As we ploughed through our second pint in one of Belgravia’s best-kept-secret pubs, I asked how life was treating him. Surprisingly, despite his new-found wealth, he was strikingly melancholic. He spoke far more warmly about the life he had left behind than the new one he had built.
He is not alone; I have had similar conversations with several clients who relocated overseas and while their circumstances may differ, they feel the same. Financially, the decision to move abroad makes perfect sense but personally, they have doubts. Strip away the monetary and/or tax advantages and most, if not all, openly admit that they regret leaving.
Of course, some expatriates genuinely enjoy their new lives, and Britain has hardly made staying an easy choice. Increasing taxes, political hostility towards wealth and ever-changing rules and regulations have encouraged successful people to look elsewhere. On a spreadsheet, relocating can appear entirely rational.
But spreadsheets cannot measure Sunday lunch with parents, friendships built over decades, familiar countryside, pub crawls, changing seasons or the quiet comfort of simply belonging somewhere. These things don’t appear on a balance sheet but are more valuable than anything that does.
The decision therefore raises an important question: how should we value time against money? When we are young, money is scarce and time feels almost infinite. Exchanging our hours for income is necessary and sensible; we work hard to build careers or businesses and take risks to create security.
As we get older, however, that equation changes. Money (hopefully) becomes more plentiful but our remaining supply of time contracts. And yet our behaviour often fails to adjust. People who already possess more wealth than they are ever likely to spend continue sacrificing years of their lives to accumulate even more of it.
Financial markets offer an interesting analogy. A futures investment exposed to contango – whereby the futures prices of an asset is higher than its current spot price – can gradually lose value as contracts are repeatedly rolled forward at higher prices, even when the underlying asset itself goes nowhere.
Time behaves almost in reverse. Its available supply diminishes every day, so each remaining year should theoretically become more valuable than the last. Yet many of us continue trading today’s increasingly valuable years in exchange for money, an asset whose marginal value is declining over time.
Perhaps we assume those years can be repurchased later. One more deal, one more bonus or five more tax-efficient years and then we will return to the UK and begin enjoying life. But future time is not necessarily the same product; it may arrive with less energy, poorer health, ageing parents and children who no longer want to spend their holidays with us.
For someone struggling to pay the mortgage, exchanging time for money is unavoidable. But once genuine financial security has been achieved, surely the trade should begin to reverse? Money should increasingly be used to buy freedom, health, experiences and time with the people we love.
This is not really an argument about Dubai, it is about recognising when enough is enough and understanding that wealth is only truly valuable when it gives us greater control over how and more importantly where we spend our finite lives.
Given the many conversations I’ve had with clients over the years about this topic, my suspicion is that many British expatriates are not permanently lost at all but simply waiting for the calculation to change. If the UK became even marginally more welcoming towards wealth creation, and slightly less determined to tax it at every turn, I suspect we would witness a tsunami of expatriates returning to this green and pleasant land.
For London, this calculation is already beginning to swing with prime central London property values now sitting broadly 50 per cent lower, in real terms, than in 2014. Just because you choose not to be tax-resident does not mean you can’t take advantage now for when you return in the future. This is a growing trend I am seeing among ex-pat clients who initially left Britain to preserve their money but will ultimately return to preserve their time.
About the Author
More articles
by author
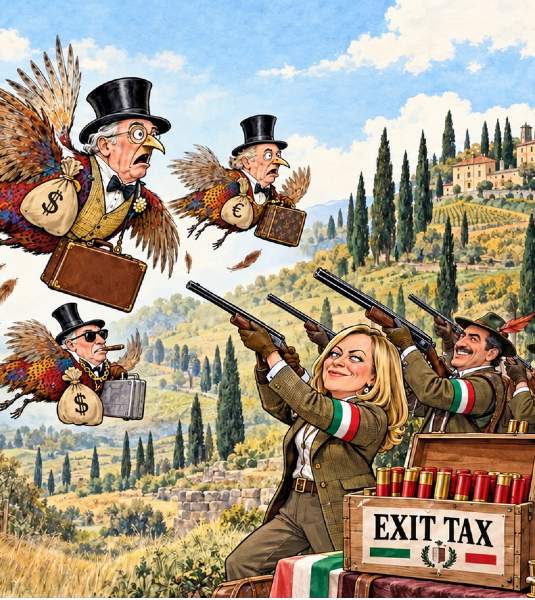
Ciao! Arrivederci!
A draft 2027 Budget has been released in Rome by Giorgia Meloni’s Government
READ ARTICLE
With London's property boom in reverse, is there a buying opportunity? (The Financial Times)
“The divergence in values between central London and outer London has narrowed to the point where you don’t have to be ultra-wealthy to own a home in Chelsea,” says Ollie Marshall, director of Prime Purchase. “We’re essentially seeing a repatriation of central London assets that were held by international foreigners to UK buyers.”
READ ARTICLE
London's Burning
Back in 1666, in a bakery in Pudding Lane, a fire broke out, which destroyed no less than 80 per cent of the City of London.
READ ARTICLE
From funk to philanthropy
In 1991, the Red Hot Chili Peppers released ‘Give It Away’, an iconic rock anthem that became one of their defining hits. What most fans don’t realise is that despite the vaguely demonic video the song’s origins are deeply rooted in generosity.
READ ARTICLE
Kubrick's warning on AI
Back in 1968, when Stanley Kubrick’s 2001: A Space Odyssey first appeared in cinemas, he imagined that 2001 would see the dawn of commercial space travel, lunar colonies and sentient artificial intelligence. While we did eventually get the AI part and recently sent astronauts further than ever, interstellar travel still alludes us, although it will be a step closer after Elon Musk’s long-anticipated IPO of SpaceX later this year.
READ ARTICLE
Hold the line
In January 1944, Allied forces were stuck south of Rome, bogged down in the Italian winter. The Germans had spent months constructing the Gustav Line, a complex layered defensive system running through Monte Cassino, across rivers, mountains, and ruined villages. It was formidable and impenetrable as concrete bunkers coupled with interlocking fire from the strategic advantage of higher ground.
READ ARTICLE
Crude awakenings – 'the fracas in Caracas'.
In the early hours of 3 January, and in a scene straight out of a Tom Clancy thriller, an elite US Delta Force team swept through Caracas seizing Venezuelan president Nicolás Maduro. As of last week, he now resides in the Metropolitan detention centre in New York alongside other current and former residents such as Sean ‘Diddy’ Combes, Ghislaine Maxwell, Sam Bankman Freud, the late Geoffrey Epstein and ironically El Chapo.
READ ARTICLE
Putting the Budget into perspective.
On the night of 29 December 1940, Londoners went to bed knowing the Luftwaffe would come again. By dawn, St Paul’s Cathedral was shrouded in smoke and dust, the only thing visible through the flames that consumed much of the City.
READ ARTICLE
The anti-bubble.
In 1957, in a garage in Hawthorne, New Jersey, two entrepreneurial engineers named Alfred Fielding and Marc Chavannes came up with what they thought would be the next big thing in interior design. By sticking two plastic shower curtains together with pockets of air trapped within it they created a futuristic textured wallpaper. Unsurprisingly perhaps, it never caught on.
READ ARTICLE
Advance to Mayfair: British buyers roll the dice in prime central London once again.
“Go to jail, go directly to jail, do not pass Go, do not collect £200” – that, more or less, is the message Prime Central London received from the Chancellor, with the Budget still two months away. Capital gains tax on primary residences? Perhaps. Replacing stamp duty with an annual levy? Possibly. Dusting off the old mansion tax? Don’t rule it out. The result, a two-month hiatus in transactions and, ironically, an even larger hole in Rachel Reeves’ already-stretched fiscal plans.
READ ARTICLE
Starboard!
Britain is setting sail on choppier seas, with the Government committing billions to bolster its naval firepower and the Royal Navy enjoying a renaissance.
READ ARTICLE
DOGEball
“If you're going to become true dodgeballers, then you've got to learn the five d's of dodgeball: dodge, duck, dip, dive and dodge!”
READ ARTICLE
The gift horse
In his letter to the Ephesians in 400AD, St Jerome wrote: ‘Noli equi dentes inspicere donati’ (never inspect the teeth of a given horse).
READ ARTICLE
BRICS and mortar
This week, Russian President Vladimir Putin hosted a gathering of no less than 36 international leaders at the annual BRICS summit in Kazan.
READ ARTICLE
Shaken not stirred
In 1956, Ian Fleming penned what has become arguably one the most iconic catchphrases on the silver screen.
READ ARTICLE
D-Day for the central banks
This month marks the 80th Anniversary of the D-Day invasion where we commemorate the bravery and sacrifice of those who fought during a pivotal moment in World War II.
READ ARTICLE
A Hedge too far
The humble hedge is a quintessentially British feature of our landscapes and gardens.
READ ARTICLE
Enter the Dragon
Back on 19 August 1973, Enter the Dragon, arguably the most popular martial arts film of all time, premiered in Los Angeles.
READ ARTICLE